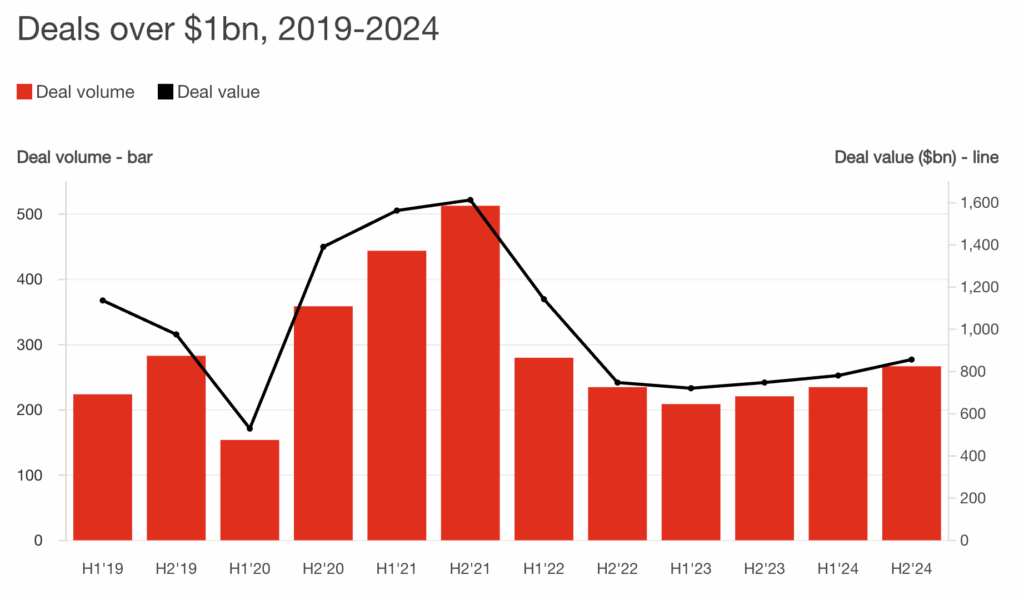
According to PwC, the global M&A market is rebounding as economic and geopolitical uncertainties ease. Still, the outlook for 2025 remains uncertain. Large deals ($1bn+) saw a 17% rise in volume in 2024, with higher average values, signaling an upswing. However, smaller and mid-sized deals declined by 18%, indicating mixed trends.
There are many reasons for merger failures, ranging from poor strategic planning to cultural clashes. Understanding them is crucial for anyone involved in the M&A process, from executives and managers to investors and advisors.
In this article, we’ll explore ten unsuccessful mergers and acquisitions examples, investigate the key reasons why these deals failed, and discuss strategies to avoid such failures in the future.
Let’s start with a brief overview of the worst mergers in history, and then we’ll move on to a detailed description.
| Companies involved | Year | Deal value | Financial losses |
| 1. Microsoft and Nokia | 2013 | $7.2 billion | $7.5 billion |
| 2. Caterpillar and ERA | 2012 | $677 million | $580 million |
| 3. Bank of America and Countrywide | 2008 | $4 billion | $9 billion |
| 4. Google and Motorola Mobility | 2012 | $12.5 billion | $12.5 billion |
| 5. Sprint and Nextel Communications | 2005 | $35 billion | $30 billion |
| 6. America Online and Time Warner | 2000 | $164 billion | $99 billion |
| 7. Mattel and the Learning Company | 1998 | $3.8 billion | $430 million |
| 8. HP and Autonomy | 2011 | $11.1 billion | $4 billion |
| 9. Quaker Oats sold Snapple | 1997 | $1.7 billion | $1.6 billion |
| 10. AT&T and Time Warner | 2018 | $85 billion | $40 billion |
Year: 2013
Value: $7.2 billion
Initial goal: Integrate Microsoft’s software with Nokia’s hardware expertise to boost Windows Phone sales and compete with dominant players like Apple and Samsung.
Losses: $7.5 billion
Reasons for failure: challenges in competing effectively in the rapidly evolving mobile market dominated by other players like Apple and Samsung.
One of the worst business deals in history occurred in 2013 when Microsoft acquired Nokia’s devices and services business for $7.2 billion. The aim was to integrate Microsoft’s software with Nokia’s hardware expertise to boost Windows Phone sales, which were declining rapidly compared to Android and iOS.
However, despite the acquisition, Windows Phone’s market share continued to decline, plummeting from about 3% in 2013 to less than 1% by 2016. Nokia’s Lumia phone line, which saw its unit sales peak in 2013 at over 30 million, capturing nearly 11% of the global smartphone market, fell to just 8.6 million units by 2016.
The key reasons for this failure were challenges in integrating the two companies’ operations, confusion regarding branding strategies, and the relentless dominance of Android and iOS in the smartphone market.
The rapid decline in Lumia sales led to massive financial losses for Microsoft, prompting a $7.5 billion write-down in 2015. Thousands of workers were laid off and in 2016 Microsoft sold Nokia’s feature phone business for just $350 million.
Year: 2012
Value: $677 million
Initial goal: Gain traction in the Chinese coal market through the acquisition of ERA Mining Machinery.
Losses: $580 million
Reasons for failure: inadequate and insufficient due diligence process.
Caterpillar, the world’s leading machinery manufacturer, acquired ERA Mining Machinery Ltd for $677 million in 2012. ERA was the holding company for Zhengzhou Siwei Mechanical & Electrical Equipment Manufacturing Co Ltd, one of China’s largest manufacturers of coal mine roof supports. The deal aimed to help Caterpillar gain traction in the Chinese coal market, but it soon became one of the worst acquisitions of all time.
The reason for that was significant accounting issues found shortly after the acquisition in November 2012, during an interrogation of Wang Fu, Siwei’s chairman, by Caterpillar lawyers. By January 2013, Caterpillar publicly announced the discovery of “deliberate, multi-year, coordinated accounting misconduct” at Siwei, leading to the termination of Wang’s employment.
The consequences were severe for Caterpillar, which had to take a massive non-cash charge of $580 million, 86% of the deal’s value. Despite claims of being caught off guard, evidence suggests that Caterpillar had overlooked or disregarded warning signs of accounting irregularities at Siwei before the acquisition. This negligence led to significant financial losses and damaged reputation.
Year: 2008
Value: $4 billion
Initial goal: Strengthen the position of Bank of America in the mortgage market.
Losses: $9 billion
Reasons for failure: the housing market collapse coupled with substantial legal expenses.
In 2008, the financial giant Bank of America acquired Countrywide, once the US major mortgage lender, for $4 billion. Bank of America saw the acquisition as a strategic move to solidify its position as a leading player in the commercial banking sector. But it soon turned out to be, as The Wall Street Journal put it, “the worst deal in the history of American finance”.
The reason was simple — the merger pushed Bank of America into the mortgage market just before the housing bubble burst, which led to enormous real estate losses and huge legal fees.
More precisely, Bank of America’s mortgage business lost about $9 billion in 2010 and $4 billion in 2009. Moreover, the deal with Countrywide led to various lawsuits and the bank had to pay $600 million to pension investors who claimed losses due to Countrywide’s mortgage securities and $108 million to the SEC for alleged excessive fees charged to homeowners facing foreclosure. It also agreed to a $335 million settlement to resolve accusations of discriminatory lending practices by Countrywide.
Year: 2012
Value: $12.5 billion
Initial goal: Enhance Motorola’s smartphone business and compete with Samsung and Apple.
Losses: $12.5 billion
Reasons for failure: Ongoing unprofitability, limited telecom distribution agreements, and underperformance in the smartphone market despite efforts to develop popular devices.
Google acquired Motorola Mobility to enhance its patent portfolio and strengthen its position in the competitive smartphone market, where Android was already a dominant force.
However, the acquisition faced challenges. Despite investments in flagship devices like the Moto X and Moto G, Motorola struggled with profitability, experiencing a nearly one-third revenue drop in a quarter. Limited distribution agreements with telecom providers further slowed its performance.
Nevertheless, the deal wasn’t a complete setback for Google. The acquisition granted it access to Motorola’s 17,000 patents, a valuable asset in terms of intellectual property.
In 2014, Google sold Motorola to Lenovo for $2.9 billion, allowing the company to shift its focus back to its core software and services business.
Year: 2005
Value: $35 billion
Initial goal: Merge networks and expand customer base, leveraging cross-selling opportunities.
Losses: $30 billion
Reasons for failure: clashes between two corporate cultures, incompatible network technologies, internal conflicts, and financial impairment.
In 2005, Sprint acquired a majority stake in Nextel Communications in a $37.8 billion stock purchase.
Before the deal, Sprint primarily served the traditional consumer market, offering long-distance and local phone connections. Nextel had a significant presence in the business sector, mainly because its phones were known for their press-and-talk features.
After the merger, the new entity became the third-largest telecommunications provider, behind AT&T and Verizon. By gaining access to each other’s customer bases, both companies hoped to grow by cross-selling their product and service offerings. However, several challenges hindered the deal’s success.
Firstly, the merged companies’ networks used different technologies and had no overlapping coverage areas, making integration extremely difficult. This resulted in operational inefficiencies and prevented them from providing a seamless service to customers.
Cultural differences between the companies were also an obstacle. Sprint had a bureaucratic culture, while Nextel was more entrepreneurial. Nextel employees often had to seek approval from Sprint’s management in implementing corrective actions. This led to internal conflicts and a lack of trust, which made many Nextel executives leave the company.
In 2008, the company incurred a staggering $30 billion in one-time charges for impairment to goodwill, and its stock was given a junk status rating.
Year: 2000
Value: $164 billion
Initial goal: Distribute AOL’s content across Time Warner’s vast network, capitalizing on the dot-com boom.
Losses: $99 billion
Reasons for failure: an economic downturn, technological shifts, and cultural clashes.
The deal between America Online and Time Warner is also among failed mergers and acquisitions examples. With the merger, America Online aimed to distribute its content across the two companies’ networks, capitalizing on its dominance. However, the synergy of these two dynamically different companies never materialized.
First of all, by May 2000, the dot-com bubble started to burst, and online advertising slowed down, making it hard for AOL to meet the financial expectations of the deal. Plus, the rise of high-speed internet threatened AOL’s dial-up service.
The second problem was cultural clashes. “It was beyond certainly my abilities to figure out how to blend the old media and the new media culture. They were like different species, and in fact, they were species that were inherently at war,” said Richard Parsons, the former CEO of Time Warner.
In 2002, the company reported a shocking loss of $99 billion, mainly due to a goodwill write-off, leading to a significant drop in its market cap from $226 billion to just $20 billion.
Year: 1998
Value: $3.8 billion
Initial goal: Enhance Mattel’s product line with educational software and interactive games.
Losses: $430 million
Reasons for failure: a lack of synergy and inadequate mission vision.
The deal between Mattel, a prominent toy manufacturer, and The Learning Company, an educational software firm, seemed like a great strategic move to enhance Mattel’s high-tech product line. But almost immediately after the acquisition, problems emerged as dealers returned unsold units.
Despite The Learning Company’s previous successes in the interactive gaming industry, including titles like “Where in the World is Carmen Sandiego?” and “Myst,” it failed to deliver any significant new hits in the years leading up to the acquisition. Instead, it incurred substantial losses, amounting to $206 million for the twelve months. This contributed to Mattel’s overall loss of $86 million for the 1999 calendar year.
The acquisition’s problems had far-reaching consequences, leading to the departure of Mattel’s Chief Executive Officer, Jill Barad, after a difficult three-year tenure. The deal failure also resulted in the resignation of Mattel’s Chief Financial Officer, Harry Pearce.
In October 2000, Mattel announced the selling of The Learning Company to Gores Technology Group, a closely held company that specializes in acquiring and turning around undervalued technology companies. According to the deal, Mattel received no cash upfront. Moreover, it retained $500 million in The Learning Company debt and recorded an after-tax loss of $430 million as a result of the sale.
Year: 2011
Value: $11.1 billion
Initial goal: Make HP an enterprise software and services leader, moving away from its traditional hardware business.
Losses: $4 billion
Reasons for failure: Inflated financials by Autonomy, leading to legal issues and a loss of shareholder value; difficulties in integrating the two companies due to differing corporate cultures and business models.
The Autonomy acquisition quickly became one of the most controversial failed mergers in tech history. Just a year after the acquisition, HP wrote down $8.8 billion, alleging that Autonomy had inflated its financials before the sale. Hewlett-Packard lost more than $4 billion over the acquisition due to an elaborate fraud masterminded by Autonomy’s co-founder, Mike Lynch, to artificially inflate the company’s value. The resulting scandal triggered numerous lawsuits and a significant loss in shareholder value.
Integrating Autonomy into HP’s operations was also challenging, as the two companies had different corporate cultures and business models. This failed acquisition derailed HP’s efforts to establish itself as a major player in enterprise software and left the company with financial and reputational damage.
Year: 1997
Value: $1.7 billion
Initial goal: Expand Quaker Oats’ beverage portfolio.
Losses: $1.6 billion
Reasons for failure: a mismatch between Quaker Oats’ approach and Snapple’s identity.
In 1993, Quaker, a food and beverage company, acquired Snapple for $1.7 billion, outbidding competitors like Coca-Cola, in a move to expand its beverage portfolio. Quaker Oats, known for its successful acquisition of Gatorade, wanted to replicate its triumph with Snapple, but soon appeared among the worst merger and acquisition failure examples.
Following the merger, Quaker Oats launched a new marketing campaign to expand Snapple’s presence in grocery stores and chain restaurants, seeking broad distribution. However, their efforts failed miserably. This is because a significant portion of Snapple’s sales were coming from small, independent stores, such as convenience stores and gas stations. Snapple struggled to maintain its market share in large grocery stores.
Two years following the purchase, Quaker Oats sold Snapple to a holding firm for only $300 million, resulting in a staggering loss equivalent to $1.6 million for each day that the company owned Snapple.
Year: 2018
Value: $85 billion
Initial goal: Merge AT&T’s distribution networks with Time Warner’s content, expanding subscription offerings for a broad customer base.
Losses: $40 billion
Reasons for failure: Conflicting business strategies, strong competition, a delayed and overpriced HBO Max launch, and AT&T’s lack of content expertise.
At the time of the merger, AT&T’s leadership was optimistic about the potential synergies between the two companies. “The content and creative talent at Warner Bros., HBO, and Turner are first-rate. Combine all that with AT&T’s strengths in direct-to-consumer distribution, and we offer customers a differentiated, high-quality, mobile-first entertainment experience,” said Randall Stephenson, chairman and CEO of AT&T Inc. “We’re going to bring a fresh approach to how the media and entertainment industry works for consumers, content creators, distributors, and advertisers.”
However, despite its promising outlook, the merger failed for several reasons.
First, the two companies had conflicting business strategies. AT&T aimed for vertical market dominance. Time Warner, in turn, focused on horizontal expansion. Second, the combined company faced intense competition from industry giants like Verizon, Disney, and Comcast.
Besides, AT&T’s delayed entry into the streaming market with HBO Max during the COVID-19 pandemic put it at a disadvantage against established platforms like Netflix and Disney+. The service’s premium pricing of $14.99 per month struggled to attract subscribers compared to lower-cost alternatives.
Ultimately, AT&T’s core expertise in telecommunications didn’t align with the complexities of content creation and distribution, leading to substantial financial losses. Three years after the merger, AT&T divested itself of Time Warner and took a $40 billion loss.
Based on an analysis of 40,000 M&A deals over the past 40 years, Fortune’s research reveals a startling truth: 70-75% of mergers and acquisitions fail.
Despite the promise of growth, innovation, and market dominance, many M&A deals fall short of expectations. So, what breaks the deals?
The decision to pursue corporate acquisitions often comes from an impulsive desire to fix a company’s struggles. Instead of exploring alternatives such as developing internal capacity through patents, brands, partnerships, or joint ventures, options that often have a higher return on investment, CEOs frequently succumb to pressure from investors and the counsel of commission-driven investment bankers.
Faced with sales slowdowns or competitive challenges, they seek a quick, transformative acquisition, which can result in overpaying for a strategic misfit target and failing to integrate it properly. In reality, acquisitions should be considered a last resort, not the first solution to a company’s issues.
Certain target attributes can significantly reduce the likelihood of success in an acquisition. Fortune’s research identified several key characteristics that often contribute to the failure of M&A deals:
Example: Lessons From General Electric Show Why We Need a Merger Cap – ProMarket
One of the most troubling factors behind M&A failure is how executives are incentivized. Many CEOs receive significant bonuses simply for completing an acquisition, and their compensation often increases with the company’s size post-acquisition. It leads to “tenure insurance”. Specifically, CEOs who engage in multiple acquisitions usually enjoy a longer tenure than those who pursue fewer deals. The problem is that the focus is on deal completion rather than long-term success.
Given the high failure rate of acquisitions, this emphasis on completion over outcome is a key factor in the ongoing failure of so many M&A deals. Shifting the focus from completing a deal to ensuring its success would help improve M&A outcomes across industries.
In 2023 and 2024, the following factors contributed to the challenges and failures in mergers and acquisitions activities:
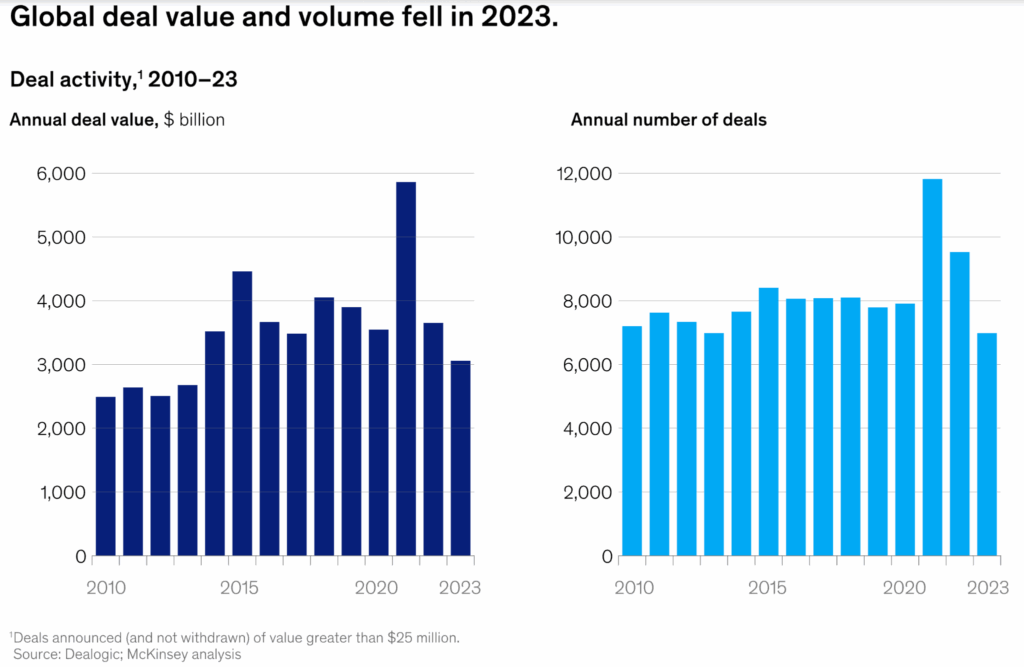
Source: Top M&A trends in 2024: A blueprint for success | McKinsey
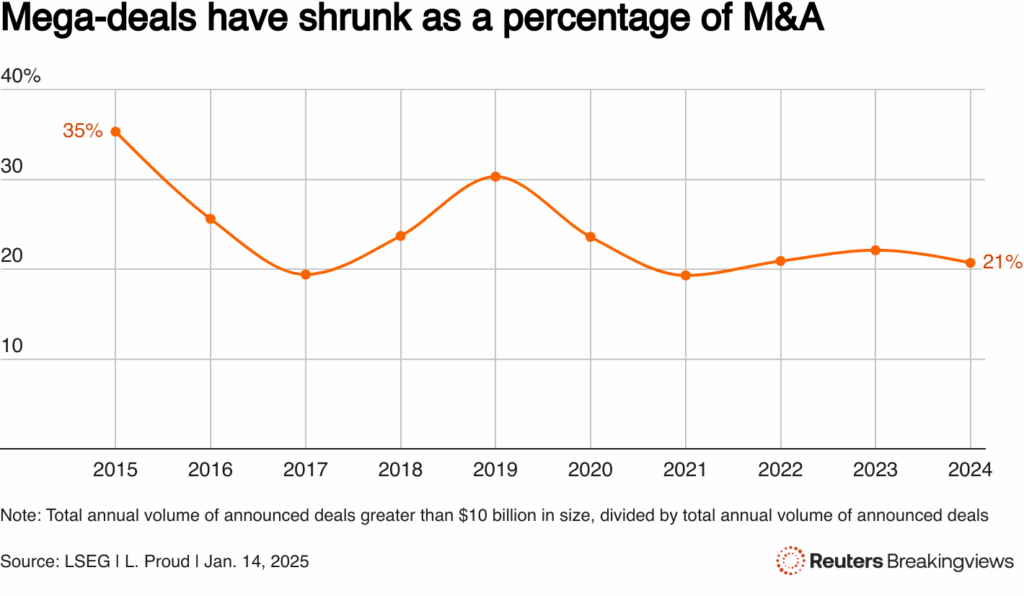
Source: Mega-merger boom threatens a shareholder bloodbath | Reuters
To avoid becoming part of these statistics, companies should prioritize thorough due diligence, develop a robust integration plan, maintain open and transparent communication with all stakeholders, and remain flexible and responsive to changing market conditions.